NOVEMBER DEBT PAYMENT RESET

For busy working Los Angeles homeowners

Cut Your Monthly
Debt Payments.
Keep More of
Your Paycheck.

Put your home equity to work on high-interest credit-card debt. Get a fresh start—and the tools to help it last.

Subject to approval. Your home secures the HELOC.

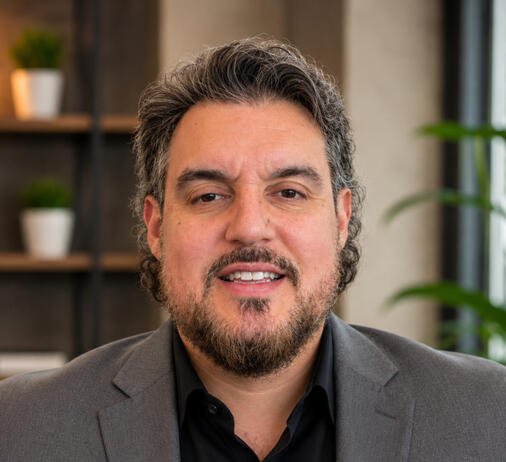
Alex Aceituno, Loan Officer and Realtor
Alex AceitunoLoan Officer & Realtor
LOS ANGELES, CA
AlexThatRealEstateGuy HELOC Advantagepowered by NEXA Lending

Your equity. Your options. Your next chapter.

✓ Keep your existing first mortgage✓ Fixed rate for the initial draw✓ A defined repayment schedule

START WITH THE NUMBERS

What could change
for your paycheck?

Use your own numbers to compare your current card payments with an illustrative fixed-rate HELOC.

1Your credit cards

Enter the totals across all your credit cards.

The example payment uses monthly interest plus 1% of the balance. Replace it with your actual combined monthly payment.


2Your home equity

Include other existing property liens in the mortgage balance.


3HELOC assumptions

Editable illustrative rate—not a personalized quote. Term and fee changes do not automatically change the rate.

Your side-by-side comparison

Compare your payments

Keep credit cards
Total credit-card debt
—
Current outstanding balance
Average APR
—
Average rate entered
Repayment term
Revolving
No fixed payoff date shown
Total monthly payment
—
Combined payment entered
Fixed-rate HELOC illustration
Total HELOC balance
—
Includes financed opening costs
Illustrative HELOC APR
—
Opening fees excluded from APR
Repayment term
—
Fully amortizing initial draw
Estimated monthly payment
—
Principal and interest

Estimated monthly payment reduction

—

Payment difference is not interest savings or debt forgiveness.

Check My Actual HELOC Options

An illustration first. Actual options after review.

Show calculation details
Debt being addressed / cash needed—
Financed origination fee—
Other financed opening costs—
Starting HELOC balance—
Combined loan-to-value after HELOC—
Scheduled HELOC payments—
HELOC interest over selected term—
Total scheduled HELOC payments—

The card payment is the total you entered, not a calculated issuer minimum. The prefilled example uses monthly interest plus 1% of the balance. No credit-card payoff time or lifetime interest is estimated.

Illustration only—not a quote, approval, or commitment to lend. Actual rates, APRs, fees, and eligibility vary. Fee calculation: card debt × fee percentage, rounded to cents, added to the debt plus other entered costs. Your lender’s fee basis may differ. HELOC APR excludes opening fees; financed fees are included in payments. Actual applicable fees are not established by this tool.

Assumes a fixed rate, fully amortizing monthly payments, timely repayment, and no additional borrowing. Totals use unrounded payments. Lower payments may increase total costs. Your home secures the HELOC; failure to repay can result in foreclosure. This payment is additional to your mortgage, taxes, and insurance. Property insurance is required; flood insurance may be required. CLTV is an estimate, not an eligibility determination.

This is a payment illustration, not a loan quote or approval. A lower payment does not necessarily mean a lower total cost.

YOU WORK HARD FOR YOUR MONEY

You make good money.
So why is debt still
keeping you up?

You’re checking balances when you should be sleeping. Doing the math again. Wondering how much longer you can keep making these payments without getting ahead.

And the hardest part? You feel like you should have this handled by now.

You want the anxiety to stop. The shame to lift. And your hard work to mean more than surviving until the next paycheck.

YOUR HOME EQUITY ADVANTAGE

A fresh start.
A way to keep it.

Eligible financing to restructure expensive debt, paired with practical tools for what comes next.

THE FINANCING

AlexThatRealEstateGuyHELOC Advantage

powered by NEXA Lending

A home equity line of credit to consolidate eligible high-interest balances while keeping your existing first mortgage in place.

  • Potentially lower combined monthly payments
  • Fewer debt payments to manage
  • Fixed interest rate for your initial draw
  • A defined payoff schedule for that draw

Your home secures repayment. Fees and repayment length affect total costs.

THE FINANCIAL FOLLOW-THROUGH

30-Day
Personal Finance Reset

Launch inclusion

Don’t let your fresh start become another debt cycle. Seven practical components you put into action yourself.

  1. 01

    Credit-Card Reload Prevention

    Create rules for card use, activate alerts, and remove stored cards.

  2. 02

    No-Fee Banking

    Organize checking and savings around your needs.

  3. 03

    Conscious Spending

    Give your income a purpose before you spend it.

  4. 04

    Paycheck Automation

    Schedule bills and transfers around payday.

  5. 05

    Emergency Savings

    Build a cushion for expenses you didn’t see coming.

  6. 06

    Guilt-Free Spending

    Know what you can spend after covering your obligations.

  7. 07

    Simple Investing

    Education on diversified, low-cost funds and getting started.

Included for the first five eligible launch homeowners who obtain their HELOC through Alex.

A CLEAR PATH FOR YOUR FIRST MONTH

Put your reset into motion.

DAYS 01–07

Build the foundation.

Credit-card reload prevention and banking.

DAYS 08–14

Give your money direction.

Conscious spending, emergency savings, and guilt-free spending.

DAYS 15–21

Make it automatic.

Schedule bills and transfers around payday.

DAYS 22–30

Review and adjust.

Investing education, setup review, and adjustments.

LIMITED LAUNCH ENROLLMENT

Your reset.
With Alex by your side.

Enroll by November 8, 2026 for a private, live 60-minute setup session walking you through your 30-Day Personal Finance Reset.

First five homeowners
YOUR PERSONAL SETUP SESSION

Work through it together.

Walk through the seven components, get answers to your implementation questions, and leave knowing your next steps.

THE GET-IT-SET-UP GUARANTEE

Still stuck? Get another session.

Complete the required steps and attend your walkthrough. If you’re still unable to implement within 30 days, Alex will include another private 60-minute session to help you finish, at no additional cost.

Covers setup assistance—not loan approval, payment reductions, investment results, or prevention of future debt.

GET STARTED

Your Home Equity Advantage.
Three simple steps.

01

Check your options.

Review preliminary eligibility and compare payments, costs, and risks.

02

Apply for your HELOC.

Complete your application. If approved, review your actual terms before accepting.

03

Put your fresh start to work.

Use your funds to consolidate selected debts, then follow your 30-Day Personal Finance Reset.

Check my options

IMAGINE YOUR NEXT PAYDAY

Stop losing sleep over debt.
Start enjoying what you earn.

Your bills are covered. Money is moving into savings. You know what’s available to spend.

Dinner out doesn’t come with guilt. An unexpected expense doesn’t automatically go on a card. And bedtime isn’t another round of calculating balances.

Less of your paycheck going toward yesterday.
More of it available for the life you’re working for.

KNOW WHAT YOU’RE TAKING ON

Good questions.
Clear answers.

The benefits matter.
So do the tradeoffs.

Does this eliminate my debt?

No. It restructures eligible debts. You still owe the new HELOC balance, including applicable financed costs.

Am I putting my house behind credit-card debt?

Yes. You’re replacing eligible unsecured debt with debt secured by your home. Failure to repay the HELOC can lead to foreclosure.

Does a lower payment mean I’ll pay less overall?

Not necessarily. Extending repayment can lower the monthly payment while increasing total interest. Compare both payments and total costs using your actual eligible terms.

Will I lose my first mortgage’s rate?

A separate HELOC can leave your existing first mortgage and its rate in place. You’ll have an additional payment with its own terms.

How does a HELOC affect my equity?

Borrowing against your home reduces your available equity and increases the debt secured by your property. Paying down the principal rebuilds equity, assuming your property value and other mortgage balances remain unchanged.

Is the interest rate fixed?

For the fixed-rate HELOC described here, the initial draw has a fixed interest rate. Additional draws may have different rates and increase your total payment. Review your agreement for the specific terms.

What fees will I pay?

An origination fee and other applicable opening costs may apply. Financing those costs increases your balance and the interest you pay. Review the complete fee disclosure before accepting.

Will I have fewer payments to manage?

Paying off selected credit-card balances with the HELOC can replace those payments with a single HELOC payment. Your existing mortgage and any debts you don’t consolidate remain separate.

What happens if I use my credit cards again?

You could end up owing both new credit-card balances and the HELOC. Consolidation doesn’t fix spending or cash-flow habits; your 30-Day Personal Finance Reset helps you establish practices to avoid rebuilding card debt.

How do I decide whether it makes sense?

Review your actual eligible options, fees, proceeds, and repayment structure. Your decision resources include a payment comparison and a comparison of keeping current debts, using a HELOC, or using unsecured consolidation.

LET’S EXPLORE YOUR OPTIONS

Explore Your
Home Equity
Advantage Options.

Complete the steps to submit your HELOC information for review.

  1. 01
    Your propertyThe home behind your equity
  2. 02
    About youYour borrower information
  3. 03
    Your financesIncome and employment
  4. 04
    Review & submitAuthorizations and contact consent

This form does not itself initiate a credit pull. Financing is subject to lender review and approval.

Prefer to talk first? Book a free consultation

Property InformationStep 1 of 4

Property Information

YOUR NEXT MOVE

Keep more of
your paycheck.

See whether your equity and eligible financing terms could make your monthly debt payments more manageable.

Check my Home Equity Advantage options
First five homeowners · Enroll by November 8, 2026 for the live-session bonus